 Charles Thomson - Head of Portfolio Management
Strong Rally in Global Bonds as Rate Hike Expectations Scaled back
In October 2026, U.S. Treasury markets rallied strongly, with yields falling significantly across the curve as investors reacted to a softer-than-expected employment report and growing expectations that economic momentum may be moderating. While inflation surprised to the upside, with CPI rising from 3.4% to 3.7%, the bond market largely looked through the near-term inflation pressure, focusing instead on signs of a cooling labour market and the prospect of a more accommodative policy outlook. Economic data sent mixed signals, however, as consumer confidence remained exceptionally strong, highlighting the continued resilience of household spending and suggesting that recession risks remain limited. Looking ahead, investor attention is increasingly turning to the upcoming U.S. midterm elections, where current polling and political trends point to a potentially strong outcome for Democrats, a development that could influence expectations for fiscal policy and Treasury supply dynamics in 2027. We have significantly pared back our expectations for additional policy tightening. Beyond a final 25 basis point rate hike in December, we expect the Federal Reserve to keep rates unchanged throughout 2027 as growth moderates and inflation gradually returns towards target.
UK gilts delivered mixed performance in October 2026, with the yield curve flattening as short-dated yields rose while longer-dated yields declined. Front-end yields moved higher as investors increasingly priced in further monetary tightening, with inflation remaining uncomfortably elevated and markets assigning a high probability to a Bank of England rate hike at the 5 November MPC meeting. In contrast, longer-maturity gilts benefited from expectations of weaker economic growth and a more limited policy path beyond the near term, resulting in lower long-end yields and a flatter curve overall. Attention also focused on the 28 October Budget, which proved largely uneventful from a gilt market perspective. The absence of significant fiscal surprises or additional borrowing requirements was well received by investors, helping to support longer-dated bonds. As a result, the month was characterised by a flattening of the curve, with fiscal stability underpinning the market while expectations of imminent monetary tightening weighed on short-maturity gilts.
European government bonds experienced a divergent month in October 2026, driven largely by developments in France. Concerns over France’s deteriorating fiscal position and the prospect of rising government borrowing requirements weighed heavily on French sovereign debt, leading to a significant widening of OAT-Bund spreads as investors demanded greater compensation for holding French risk relative to German government bonds. The move reflected growing unease over the sustainability of France’s public finances and the potential implications for its sovereign credit profile. However, sentiment improved markedly towards month-end following Moody’s decision to leave France’s sovereign rating unchanged, surprising many market participants who had feared a downgrade. The rating affirmation helped alleviate immediate fiscal concerns and triggered a recovery in French government bonds, with OATs outperforming core European markets as spreads versus Bunds narrowed from their widest levels. As a result, while fiscal concerns remained a key theme, the month ended with a partial reversal of the earlier underperformance in French sovereign debt.
Japanese government bonds rallied strongly in October 2026, with gains led by the long end of the curve as investors increasingly looked beyond near-term policy normalisation and focused on a more benign inflation and growth outlook. Long-dated JGB yields declined by around 30 basis points during the month, significantly outperforming shorter maturities and reinforcing the attractiveness of Japan’s still-steep yield curve. In our view, the curve continues to offer compelling value, particularly at longer maturities where term premia remain elevated relative to the likely trajectory of interest rates. We also remain bullish on the Japanese yen, which offers an attractive asymmetric return profile. While further appreciation could be supported by narrowing interest-rate differentials and any repatriation of overseas capital, downside risks appear more limited, not least because renewed yen weakness would increase the likelihood of policy intervention by Japanese authorities. As a result, we continue to view both long-duration JGB exposure and the yen favourably within a global fixed-income portfolio.
Chinese government bonds were broadly stable in October 2026, with yields moving only modestly lower across the curve as subdued domestic inflation and accommodative policy expectations continued to support the market. Returns were driven primarily by carry rather than significant capital appreciation, with yield movements remaining relatively contained compared with other major government bond markets. The renminbi strengthened further against the US dollar during the month, extending its recent recovery and providing an additional source of return for unhedged investors. Chinese government bonds continue to offer valuable diversification benefits within a global fixed-income portfolio, reflecting their relatively low correlation with developed-market interest rates and distinct domestic policy cycle. While we remain constructive on the asset class from a portfolio diversification perspective, the scope for substantial capital gains, particularly at the short end of the curve, remains limited given already low yield levels. As such, the principal attraction of short-dated Chinese government bonds continues to be their defensive characteristics and diversification benefits rather than expectations of meaningful price appreciation.
Emerging market debt delivered positive returns in October 2026, benefiting from the sharp rally in US Treasuries as declining developed-market yields provided a supportive backdrop for hard-currency sovereign debt. The fall in US yields generated meaningful duration gains, more than offsetting generally stable credit spreads, while the asset class continued to benefit from its attractive carry profile. Local-currency debt also performed well, supported by lower domestic bond yields in several markets and a generally more favourable environment for emerging market currencies as the US dollar weakened. Performance was broad-based, with both sovereign and corporate segments contributing positively. While credit spreads remain relatively tight by historical standards, the combination of elevated all-in yields, improving global liquidity conditions and a less challenging US rates environment continues to support the asset class. We remain constructive on emerging market debt, particularly in countries with credible policy frameworks and attractive real yields, where investors can continue to benefit from both carry and the potential for capital appreciation should global rates remain on a declining trajectory.
The following chart shows the 2-year US Treasury yield, which declined 30bp in October 2026
2-Year US Treasury Yield
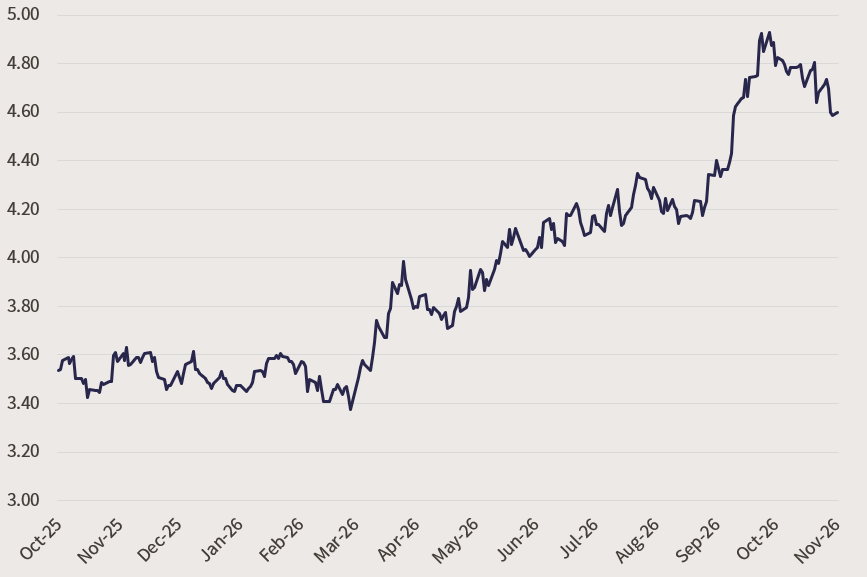
Source: Bloomberg Finance L.P., 31 October 2026.
|
 Download Commentary >